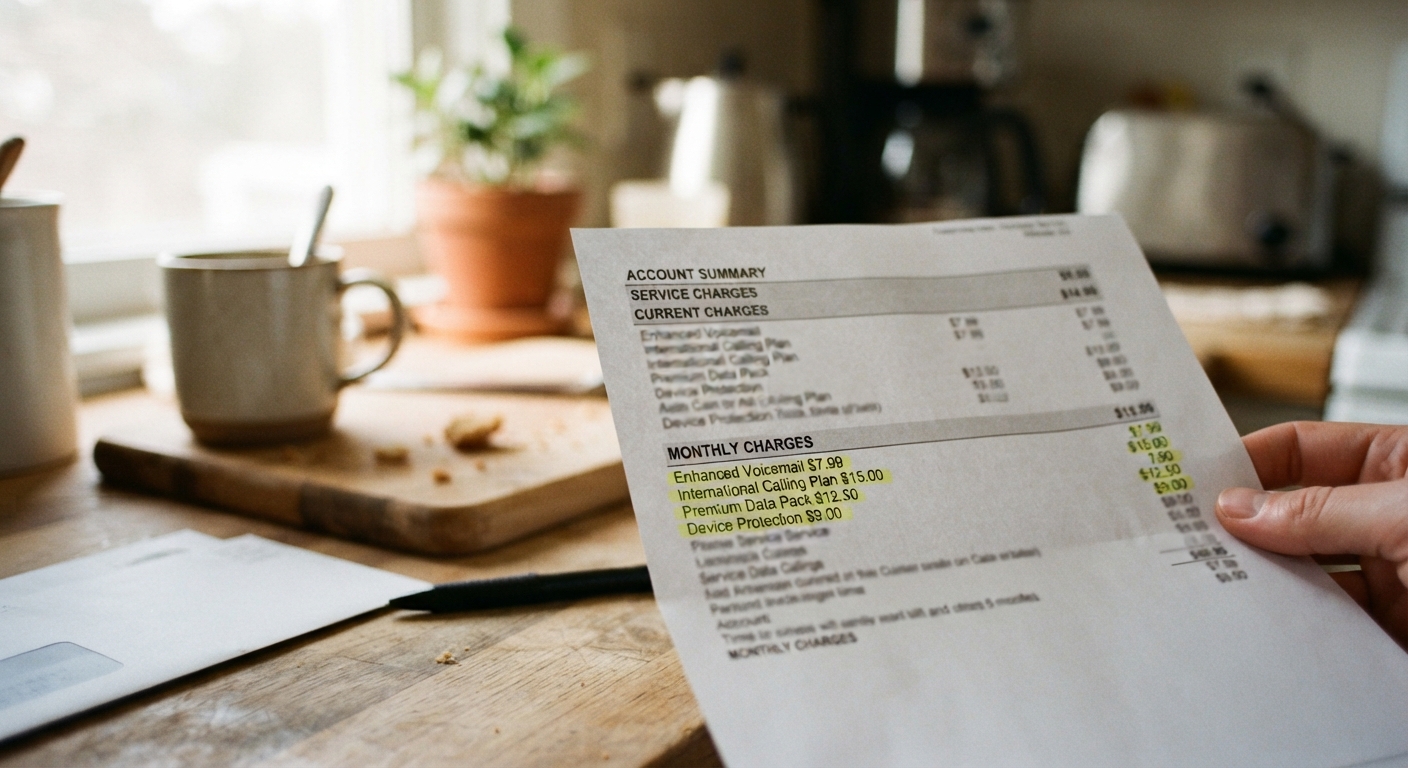
Open your phone bill right now — actually pull it up. Somewhere in that itemized list, there’s a decent chance you’ll find a charge for something you don’t remember signing up for, don’t use, and could stop paying for today. That’s not an accident. It’s how the business is built.
Why carriers default customers into add-on services at signup
When you sign up for a new phone plan or upgrade a device in-store, the person helping you is usually working from a script that includes a handful of “recommended” extras. Device protection plans, cloud backup subscriptions, streaming bundles, international calling packs — these get mentioned quickly, often framed as free for the first month or two, and tacked on before you’ve fully decided what you actually need.
This isn’t necessarily shady on the part of the individual rep. Carriers structure their incentives so that add-ons get pushed hard, because the profit margin on a $12 monthly insurance rider or a $3 cloud storage upgrade is often better, over time, than the margin on the phone plan itself. A customer who takes the bait once and never looks again is worth more every single month than one who signs up for the bare plan and nothing else.
The “free trial” period is doing a lot of quiet work here too. If a service auto-enrolls you for 30 or 60 days at no charge, most people forget it exists by the time billing kicks in. You get busy, the charge is small, and it blends into a bill full of taxes, fees, and line items that already look confusing. Multiply that by however many phone lines are on your family plan, and you can end up with three or four small subscriptions stacked on top of each other, none of which anyone in the house is actively using.
None of this means you were careless for missing it. It means the system is designed so that missing it is the default outcome unless you go looking.
How to read your itemized bill to find recurring add-on charges
Most people skim their phone bill for the total due and move on. To find hidden add-ons, you need to look at the breakdown by line, not just the summary at the top.
Start by logging into your carrier’s app or website rather than relying on the paper or PDF summary, since the online version usually lets you expand each phone number on your account into its own itemized section. Every line on a family or shared plan can carry its own separate add-ons, so a charge under your teenager’s line might be completely different from what’s attached to yours.
Once you’re in the itemized view, look for three categories of charges:
Plan charges — this should match whatever base plan you actually signed up for. If this number has crept up without you changing plans, that’s worth investigating separately from add-ons, but it’s good to confirm it’s accurate first.
Equipment charges — this covers device payments if you’re financing a phone, plus any protection or insurance plans tied to that device.
Services and features — this is usually where the add-ons live. Look for anything with words like “protect,” “plus,” “premium,” “cloud,” “unlimited,” or a specific app or brand name (streaming services in particular). If you see a charge and can’t immediately say in one sentence what it does for you, write it down.
A useful habit is to compare your last three bills side by side, even just the totals for each line item. If a charge has been sitting at the exact same dollar amount for months and you can’t recall the last time you used whatever it’s for, that’s your signal. Genuine plan charges tend to shift when you change plans or add a line; forgotten add-ons tend to sit there quietly, unchanged, for years.
Common add-ons worth canceling: device protection overlaps, cloud storage, entertainment bundles
Not every add-on is worth cutting — some people genuinely use and want theirs. But a few categories are worth checking closely, because they’re the ones most likely to be either redundant or simply unused.
Device protection overlaps
Phone insurance and device protection plans are one of the most common places where people end up paying twice for the same coverage. If you have renters insurance, check whether it already covers personal electronics against theft or damage — many policies do, at least partially, and you may be carrying a separate carrier-based protection plan on top of it for no real added benefit. Similarly, some credit cards include a limited form of purchase protection or extended warranty coverage on things bought with that card, which can overlap with what the carrier is charging you for separately. This is worth double-checking directly with your insurance provider or card issuer rather than guessing, since coverage details vary, but it’s a common enough overlap that it’s worth the ten minutes to look.
Cloud storage upgrades
Carriers often bundle a paid tier of cloud backup, sometimes branded under the carrier’s own name rather than a familiar one like a phone manufacturer’s cloud service. If your phone’s operating system already includes its own backup service, and you’re not exceeding the free storage tier, a second paid cloud subscription through your carrier may be storing nothing you’re not already storing elsewhere. Check how much storage you’re actually using against how much you’re paying for — it’s common to find you’re using a fraction of what you’re being charged for.
Entertainment bundles
A lot of phone plans include a “free” streaming subscription for a limited window, after which it quietly converts to a paid add-on tacked onto your phone bill instead of billed directly through the streaming service. If your household already subscribes to that same service through another account, or has stopped using it, this is one of the easier things to cancel outright since it typically doesn’t affect your core plan pricing.
How to call and cancel without losing a discount tied to the bundle
Here’s the part that trips people up: sometimes an add-on isn’t just sitting there independently — it’s bundled into a discount on your base plan. Cancel the add-on without checking first, and you might lose $10 off your monthly plan to save $6 on the add-on, which is a net loss.
Before you cancel anything, ask the representative directly: “Is this service linked to any discount on my plan, and if I cancel it, will my plan price change?” Get a clear yes or no answer before you agree to remove anything. Reps can see this on their end even if it’s not obvious to you from your bill, so make them spell it out rather than assuming.
A few things that make these calls go faster and get better outcomes:
Call rather than trying to cancel entirely through the app, at least for anything bundled with a discount. Self-service cancellation tools are often built to remove the standalone charge cleanly, but they’re not always good at flagging linked discounts, and you can end up losing a bundled rate without any warning on screen.
Have your account number and the specific line item name in front of you when you call, exactly as it appears on your bill. Vague requests like “cancel my extra stuff” tend to get vague answers back. Naming the specific charge gets you a specific answer.
Ask for confirmation in writing — most carriers can send a text or email summary of the change while you’re still on the call. This gives you something to point back to if the charge reappears next month, which does happen more often than it should.
If you’re told that canceling one add-on will raise your plan price, ask whether there’s a different discount available now that doesn’t require you to keep the add-on. Pricing and promotions shift constantly, and reps sometimes have room to offer something better than what you’re currently on, especially if you mention you’re considering switching carriers. You don’t have to actually be shopping around to ask the question.
Finally, don’t be afraid to ask for a supervisor or a retention specialist if the first representative seems unable to separate the bundle cleanly. This isn’t about being difficult — it’s a normal part of how these calls go, and retention teams often have more flexibility to adjust pricing than a general customer service line.
Setting a yearly reminder to audit your bill for new charges
The most effective fix here isn’t a one-time cleanup — it’s making this a habit so the same thing doesn’t creep back in a year from now. Add-ons get reintroduced more often than people expect, sometimes through a “courtesy upgrade” after a customer service call about something else entirely, or through a promotional period that quietly converts to a paid one.
Pick a date that’s easy to remember — the same week you renew renters insurance, or right after the school year starts, or your own birthday month — and set a recurring reminder to pull up your phone bill and read through the itemized charges line by line. It takes fifteen minutes once you know what you’re looking for, and it’s the single easiest way to make sure a $5 or $10 charge doesn’t sit there unnoticed for another three years.
If you share a family plan, do this audit for every line, not just your own. Add-ons attached to a child’s line or a partner’s line are just as easy to forget, and just as easy to cancel once you know they’re there.
None of this requires a dramatic renegotiation of your whole phone plan. It’s a small, repeatable check — read the bill, ask what each charge does, cancel what you don’t need, confirm the plan price didn’t move. Done once a year, it keeps your bill matching what you actually use instead of what got added on the day you signed up.