Why insurers ask for proof of ownership and value after a loss
When something goes wrong — a pipe bursts, a break-in happens, a grease fire takes out your kitchen — the last thing you want is to sit down and try to remember, item by item, everything you owned. But that’s exactly what most renters insurance claims require. Your insurer isn’t being difficult on purpose; they legally have to verify that what you’re claiming actually existed, that you actually owned it, and that the value you’re asking for is reasonable. Without documentation, you’re relying entirely on memory, and memory is a terrible witness under stress.
This is where a lot of claims slow down or get underpaid. Adjusters aren’t trying to shortchange you, but they can only pay for what can be verified. If you say you had “a bunch of nice kitchen stuff” and can’t say more than that, you’ll likely get a generic, low-ball estimate. If you can hand over a list with brands, approximate purchase dates, and photos showing the items in your home before the loss, the claim moves faster and the payout tends to match reality instead of a stranger’s guess.
A home inventory solves this problem before it ever becomes a problem. It’s not about being paranoid or expecting disaster. It’s about making sure that if something does happen, you’re not stuck trying to reconstruct your entire living space from memory while also dealing with the actual crisis in front of you.
The fastest way to document belongings: photos, video walkthroughs, and receipts
You do not need to catalog every fork and sock. The goal is a reasonably complete record that would let someone else — an adjuster, or future you — understand what was in your home and roughly what it was worth. The fastest way to get there is a video walkthrough, not a written list.
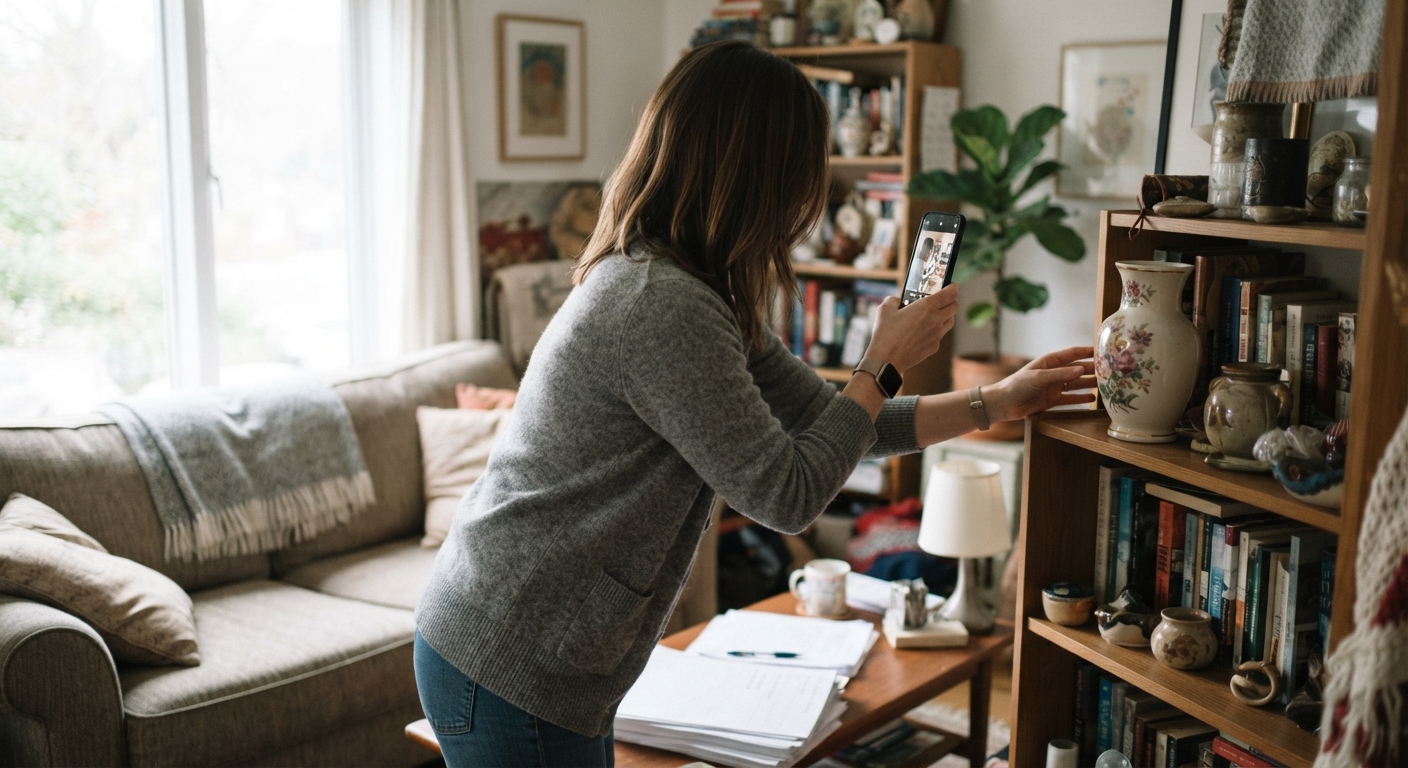
Walk through every room slowly with your phone recording, narrating out loud as you go. Open closets, drawers, and cabinets. Say what you’re looking at: “This is the couch we bought a couple years ago, it was a few hundred dollars.” “These are my kid’s soccer cleats and her tablet.” You don’t need exact prices, just honest, in-the-moment estimates. The narration matters because it timestamps your ownership and gives context that a photo alone won’t.
After the video, go back and take still photos of anything higher-value or harder to describe in passing — electronics, furniture, jewelry, tools, appliances, musical instruments, anything with a serial number. Photograph the serial number itself if you can find it; it’s usually on a sticker on the back or bottom of the item. Serial numbers are one of the strongest pieces of proof you can offer because they’re unique and hard to dispute.
Receipts round out the picture, but don’t stress about finding paper copies of everything you bought over the last decade. Focus on:
Big-ticket purchases from the last few years (furniture, electronics, appliances). Check your email — most stores send digital receipts automatically, and a quick search of your inbox for “order confirmation” or the retailer’s name will surface more than you’d expect. Bank and credit card statements can also work as backup proof of purchase even without a detailed receipt, since they show the date, amount, and merchant.
You’re not building a legal case file. You’re building a reasonably convincing, easy-to-follow record that makes an adjuster’s job simple. The easier you make their job, the faster your check shows up.
Free apps and spreadsheet templates for organizing your inventory
Once you’ve got the raw material — video, photos, receipts — you need somewhere to organize it so it’s actually useful later. You have two realistic options: a dedicated app or a simple spreadsheet. Both work fine; pick whichever you’ll actually keep updated.
Several free home inventory apps let you photograph an item, tag it with a category and estimated value, and store it in a searchable list. These are useful because they keep everything in one place and often let you export a PDF report you can hand straight to an insurer. Search your phone’s app store for “home inventory” and you’ll find a handful of well-reviewed free options — try a couple and see which interface feels natural, since you’re more likely to stick with a tool you don’t have to fight with.
If you’d rather not add another app to your phone, a basic spreadsheet works just as well and gives you more control. Set up columns for: room, item, brand/model, approximate purchase date, approximate value, and a note field for the serial number or a link to the receipt. Group rows by room so it mirrors how you’d actually walk through your home. This kind of spreadsheet takes maybe twenty minutes to set up and can be duplicated or backed up anywhere — email, cloud storage, a shared drive with a partner or roommate.
Whichever method you choose, consistency matters more than sophistication. A messy but complete spreadsheet beats a beautifully designed app you gave up on after the living room. Block out one afternoon, room by room, and treat it like a chore you’re doing once so you never have to do it under worse circumstances.
Storing your inventory somewhere it survives a fire, flood, or theft
Here’s the part people forget: an inventory only helps if it survives whatever happened to your stuff. A written list in a kitchen drawer or a folder of photos saved only to a phone that gets stolen in the same break-in does you no good at all. Your inventory needs to live somewhere separate from your home.
Cloud storage is the simplest answer. Most phones automatically back up photos and videos to a cloud account already, but don’t assume — check your settings and confirm it’s actually turned on. For your spreadsheet or exported inventory app report, save a copy to a cloud drive (the kind tied to your email account, or a dedicated cloud storage service) rather than only on your laptop’s hard drive.
It’s worth keeping a second copy somewhere else too, just in case. Email yourself the spreadsheet as an attachment — email is its own backup, sitting on a server far away from your apartment. Or share the folder with a trusted family member who doesn’t live with you, so there’s a copy outside your household entirely. The point is redundancy: if your phone, laptop, and physical papers are all destroyed or stolen at once, your inventory should still exist somewhere untouched.
A quick gut-check: if your entire home vanished tomorrow, could you access your inventory from a friend’s phone or a library computer? If yes, you’re in good shape. If the honest answer is “only if my phone survives,” it’s worth spending ten more minutes fixing that.
How a good inventory helps you avoid being underinsured in the first place
Most renters guess at their coverage amount when they sign up for a policy — a round number that sounds reasonable, like enough to “replace everything.” The trouble is, most people badly underestimate how much their belongings are actually worth once you add it all up: clothing, furniture, electronics, kitchen gear, kids’ stuff, seasonal items, the contents of every closet and drawer. A home inventory forces you to see the real total, which is often higher than what your current policy would pay out.
This matters because if your coverage limit is lower than the actual value of your belongings, you’re underinsured — and you won’t find out until you’re filing a claim and discovering the payout doesn’t come close to replacing what you lost. Going through the inventory process gives you a real number to compare against your policy’s coverage limit, which is something you can check any time, not just after a loss.
If your inventory total is noticeably higher than your coverage, that’s useful information heading into your next renewal or a conversation with your insurer. It also helps you decide whether you need any add-on coverage for specific high-value items — certain jewelry, electronics, or musical instruments sometimes have lower payout caps under a standard policy unless you specifically schedule them. You won’t know to ask about that unless you know what you actually own and roughly what it’s worth.
Think of the inventory as doing double duty: it protects you after a loss, and it helps you make sure your coverage actually matches your life right now, rather than the guess you made when you first signed up.
Updating your list after big purchases, gifts, or holidays
An inventory that’s three years out of date is better than nothing, but it’s not going to reflect the TV you bought last spring, the bike your kid got for their birthday, or the laptop that replaced the one that died. The good news is that keeping it current doesn’t require another full afternoon — just a habit of small, quick updates.
The easiest trigger points are the moments when new stuff naturally enters your home: birthdays, holidays, back-to-school shopping, or any purchase over maybe fifty dollars. When something new comes in, take thirty seconds to snap a photo, jot down the item and rough value in your spreadsheet or app, and move on. It takes far less time to log an item the day you get it than to try to remember it a year later.
It’s also worth doing a quick refresh once or twice a year — maybe when the seasons change or around when your renters insurance renews — just to walk through and check that nothing major has changed or disappeared from the list. This doesn’t need to be the full room-by-room video again; a fast scroll through your existing inventory while glancing around your space is usually enough to catch anything missing.
The whole point of building this list in an afternoon is that you never have to build it again from scratch. Small, regular updates keep it accurate with almost no ongoing effort, so it’s ready the moment you actually need it — whether that’s for a claim, a coverage check, or just knowing exactly what’s in your home.