If you have school-age kids, you already know the feeling: one week it’s a normal Tuesday with normal daycare costs, and the next week it’s spring break and suddenly you’re paying for a full week of camp, plus lunches, plus maybe a sitter for the two days camp doesn’t cover. Then summer hits and it’s not one week, it’s ten or twelve. That’s the trap. Regular daycare or after-school care is a predictable monthly line item. School breaks are not, and most household budgets simply aren’t built to absorb a spike like that without some kind of strain.
Why school breaks create a childcare cost spike most budgets aren’t built for
During the school year, care is often cheaper than people realize because school itself is covering six or seven hours of the day for free. You’re really only paying for before-school, after-school, or a sitter for a couple hours. Once school lets out, that free coverage disappears and you’re back to paying for full-day care, every single day, for however long the break lasts.
Summer is the big one. A full-day camp week almost always costs more than a week of after-school care, and when you multiply that by eight, ten, or twelve weeks, you can end up paying more for summer than you paid for daycare during an entire school semester. Spring break and winter break are smaller versions of the same problem, but they still tend to land at the worst possible time, right after holiday spending or right before a tax season crunch.
The reason this feels like it “wrecks” a budget isn’t that the total cost is unreasonable. It’s that it arrives all at once, in a lump, instead of being spread out the way your regular bills are. A $1,200 rent payment feels manageable because you know it’s coming every single month. A $1,200 camp bill in June feels like an emergency because nothing prepared you for it. The fix isn’t finding cheaper camps, necessarily. The fix is knowing the number early and breaking it into pieces before it ever becomes a lump.
How to map out every break on the school calendar before spring even starts
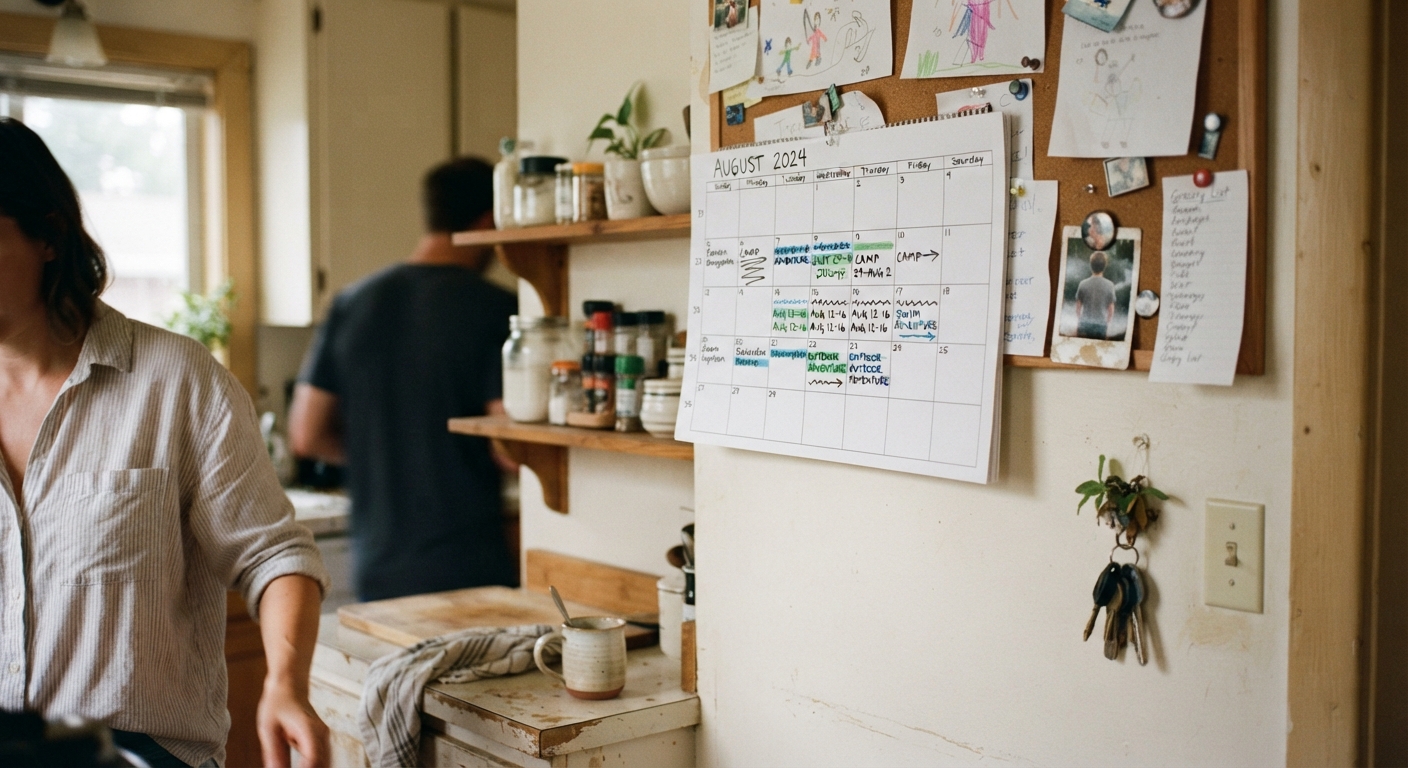
Most school districts publish next year’s calendar, or at least a draft of it, well before summer starts. As soon as you have any version of it, even a tentative one, pull out every single day school is closed and write it down in one place. Not just summer. Winter break, spring break, teacher workdays, the random Monday off for a holiday you didn’t know existed, early release days that add up to extra care hours. All of it goes on one list.
Once you have the list, count the actual days you’ll need full or partial coverage. This is the step people skip, and it’s the one that matters most. It’s easy to think “summer is about ten weeks,” but when you actually count business days, subtract any weeks you’ll have vacation or a relative helping out, and add in the smaller breaks scattered through fall and winter, the real number is often higher than the mental estimate. Write the number of days next to each break, not just the dates.
Do this mapping in late winter or very early spring, before camps open registration and before your own summer plans lock in. This gives you two things you won’t have if you wait: time to compare options, and time to start setting money aside. Waiting until May means you’re shopping for camps at the same time everyone else is, prices are less flexible, and you’re trying to find hundreds of dollars in a single month instead of spreading it over several.
Comparing camp costs, relative care, and part-time sitters for different weeks
Not every week needs to be covered the same way, and treating them all identically is usually where the budget gets bigger than it needs to be. Once you have your list of breaks and day counts, go through week by week and think about what kind of coverage actually fits.
Full-day camps make the most sense for stretches of two or more consecutive weeks, especially in summer, because many camps offer a lower per-day rate when you book multiple weeks at once compared to booking single weeks here and there. If your child only needs coverage for a scattered day or two, a camp is often the most expensive way to fill that gap, since you’re paying a weekly rate for a day or two of use.
Relative care, if you have a grandparent, aunt, or family friend who’s willing and able to help, is worth mapping onto specific weeks rather than treating as a vague backup plan. Ask early which weeks actually work for them, and treat those weeks as covered in your plan so you’re not paying for camp on days you didn’t need to.
Part-time sitters tend to work best for the short, odd-shaped gaps: a single teacher workday, the three days before winter break starts, the week camp doesn’t run but school still isn’t back in session. A sitter for a few scattered days is frequently cheaper than a week of camp tuition, especially if you can split the sitter with another family for even a portion of the time.
The goal of this comparison isn’t to find the single cheapest option and use it for everything. It’s to match each week to whichever option costs the least for that specific week, because camp, family help, and sitters all have different pricing shapes. A week-by-week plan, done in spring, almost always ends up cheaper than defaulting to “just sign up for camp” for the entire summer in June.
Setting aside a small amount monthly instead of paying the full cost in June
Once you have a real number, even a rough one, the most useful thing you can do with it is divide it by the number of months you have before you need it. If school break coverage is going to run several hundred dollars for spring break and considerably more for summer, and you start planning in January or February, you might have four or five months to spread that cost across instead of one.
A simple way to do this without opening a new account or adding complexity to your budget: pick one regular bill you already pay monthly, and add a small fixed amount on top of it into a separate envelope, jar, or savings account earmarked only for break care. Treat that extra amount exactly like a bill. It doesn’t need to be large. Even a modest amount, once you multiply it across four or five months, takes a real bite out of that eventual camp deposit or full week’s tuition.
This works because it turns an unpredictable cost into a predictable one, which is really the whole game when you’re managing a budget on a fixed or variable income. You’re not trying to find extra money in June that doesn’t exist. You’re moving small amounts of money on a schedule you control, starting when the pressure is lowest, so that by the time registration deadlines and summer bills actually arrive, most or all of the money is already sitting there waiting.
If your income varies month to month, this is even more useful, because you can put a little more into the break-care fund during a stronger month and a little less during a leaner one, as long as you’re checking in regularly against your running total and the deadline you’re working toward. The key is starting the moment you have your calendar and your rough cost estimate, not waiting until you feel like you have extra money to spare, because that month may not come on its own.
Questions to ask camps and programs about sibling discounts and early registration pricing
Camps and school-break programs often have pricing flexibility that isn’t listed clearly on their website, and the only way to find it is to ask directly, ideally before registration opens to the general public. A few questions worth asking every single program you’re considering:
Is there a discount for registering multiple weeks at once, versus booking week by week? Many programs price single weeks higher precisely because families sometimes only need one or two weeks, and the multi-week rate can bring the per-day cost down noticeably if you know to ask for it.
Is there a sibling discount if you’re enrolling more than one child? This is common enough that it’s worth asking about even if it’s not advertised, since some programs only apply it if a parent specifically requests it during enrollment rather than applying it automatically.
Is there an early registration rate, and when does it end? Many camps and programs quietly raise prices as spots fill up, meaning the family who registers in February can pay less than the family registering in May for the exact same weeks. Ask for the specific date the price changes, not just “early bird pricing,” so you know exactly when your window closes.
Is there a deposit option that locks in current pricing while letting you pay the balance closer to the date? This can be genuinely useful if you’re using the monthly savings approach above, because it lets you secure the spot and the price early while your fund is still building toward the full amount.
Are there scholarships, reduced-rate spots, or sliding-scale pricing available, and what’s the process for applying? Some programs, particularly ones run through community centers, park districts, or nonprofits, have a limited number of reduced-cost spots that aren’t widely advertised. It costs nothing to ask, and the worst answer you can get is the price you already knew.
Asking these questions in the same season you’re building your calendar and your savings plan means you’re gathering real numbers instead of guesses, which makes every other step in this process more accurate. The families who end up surprised in June are usually the ones who didn’t ask until they were already comparing final invoices. The families who plan ahead treat these questions as part of the calendar-mapping step, not an afterthought.
None of this requires a big financial overhaul or complicated tools. It’s really just three habits stacked together: know the days you need to cover well before you need to cover them, match each stretch of days to the cheapest reasonable option for that specific week, and move small amounts of money on a schedule so the total is already there when the bill shows up. Do that consistently, starting in late winter each year, and school breaks stop being the month that wrecks your budget and become just another line item you already planned for.